

CapitaLand Investment reverses into the red in H2 with S$170m loss
Jessie Lim &
Vivienne Tay
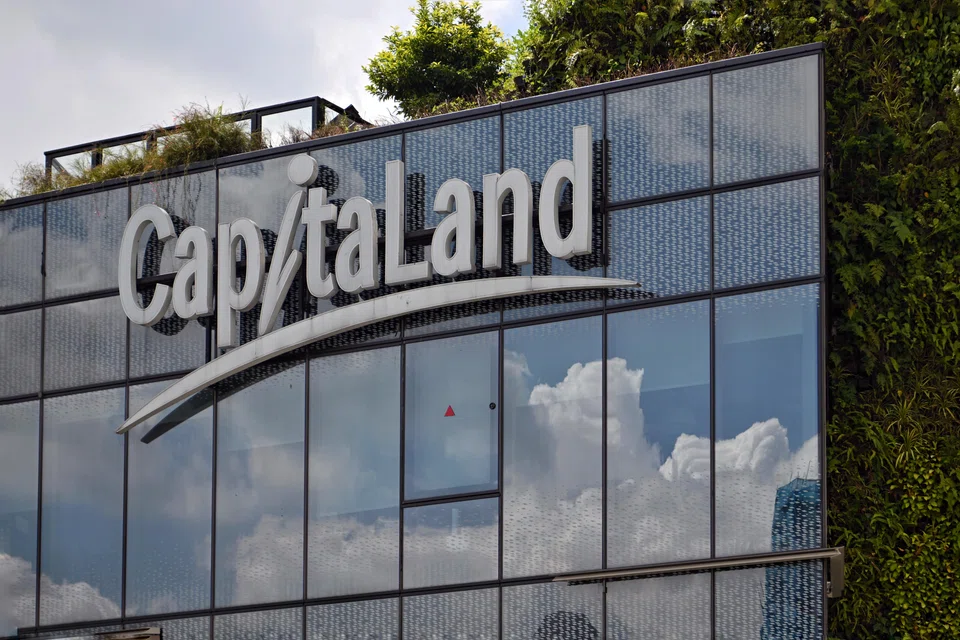
CAPITALAND Investment (CLI) slipped into the red for the second half of its fiscal year, posting a S$170 million loss compared with H2 FY2022’s net profit of S$428 million, following losses from the revaluation of its investment properties.
The fair value losses, largely from its China and United States assets, dragged full-year profit down. For the year ended Dec 31, 2023, net profit dropped 79 per cent to S$181 million from S$861 million in FY2022. In FY2023, CLI recorded S$600 million in revaluation and impairment losses, compared with revaluation gains of S$30 million in FY2022.
Speaking at the group’s H2 FY2023 financial results briefing on Wednesday (Feb 28), CLI group chief operating officer Andrew Lim said: “The fair value loss is nothing to sneeze at, but it’s 2 per cent of our investment property portfolio and is offset by pockets of strength in Singapore and India.”
Interest rate increases have led to capitalisation rate expansion in the US, and valuations for office assets have collapsed as Americans continue working from home.
In China, weak rental reversions and poor business sentiment affected valuations, said Lim.
Excluding the revaluation loss, cash profit after tax and minority interests stood at S$781 million.
CLI’s revenue for the full year was down 3.2 per cent to S$2.8 billion from S$2.9 billion in 2022.
Earnings per share fell to 3.5 Singapore cents, down 79.2 per cent from 16.8 cents in the previous corresponding period.
The group attributed the weaker performance to a drop in rental income from investment properties, partially offset by a growth in fee-related earnings.
Fee-related revenue rose 9 per cent from S$984 million in FY2022 to S$1.07 billion in FY2023, anchored by higher contributions from CLI’s lodging and commercial management businesses.
Fee-related earnings for CLI’s lodging business grew 28 per cent year on year to S$331 million, with nearly 9,600 units opening across 53 properties.
Fees from the commercial management segment increased by 11 per cent as CLI sees growing traction with its third-party contracts.
Last year, the group inked a six-year deal to manage Kallang Wave Mall and the retail spaces in the Singapore Sports Hub.
On Wednesday, CLI’s group chief executive officer Lee Chee Koon, announced that CLI will target to double its funds under management (FUM) to S$200 billion by end-2028.
To date, the group has achieved S$100 billion in FUM, including S$10 billion of funds ready for deployment based on committed capital on a leveraged basis. “Focusing on building fee income was something we were razor-focused on, and we will continue to be,” he said.
CLI plans to accelerate its pace of organic growth across its businesses, complemented by inorganic opportunities, to meet its new FUM target. “We will continue to bolster growth in our listed funds through active portfolio management, and further expand our operations and fund management in India and South-east Asia,” he added.
Manohar Khiatani, CLI’s senior executive director, said that the group’s assets under management in India have grown more than three-fold in the last 10 years and many tailwinds can be captured, in the data centres, logistics and business parks sectors.
Lee said: “We will also optimise our China portfolio and grow renminbi-denominated funds, as well as increase our fund product offerings in Japan, South Korea, Australia and beyond.”
The board has proposed a final dividend of S$0.12 per share for FY2023, unchanged from FY2022.
Shares of CLI closed S$0.04 or 1.5 per cent higher at S$2.78 on Wednesday.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

US trade chief to consider trade deal tariff caps in excess capacity probe
Bee Cheng Hiang customers’ e-mail addresses exposed in Singapore’s first case of AI-related data breach

DFI Retail to take over Starbucks business in Asia from Maxim’s Caterers

