

Hong Leong Asia expects diversifying engine product mix to improve margins
Yong Jun Yuan
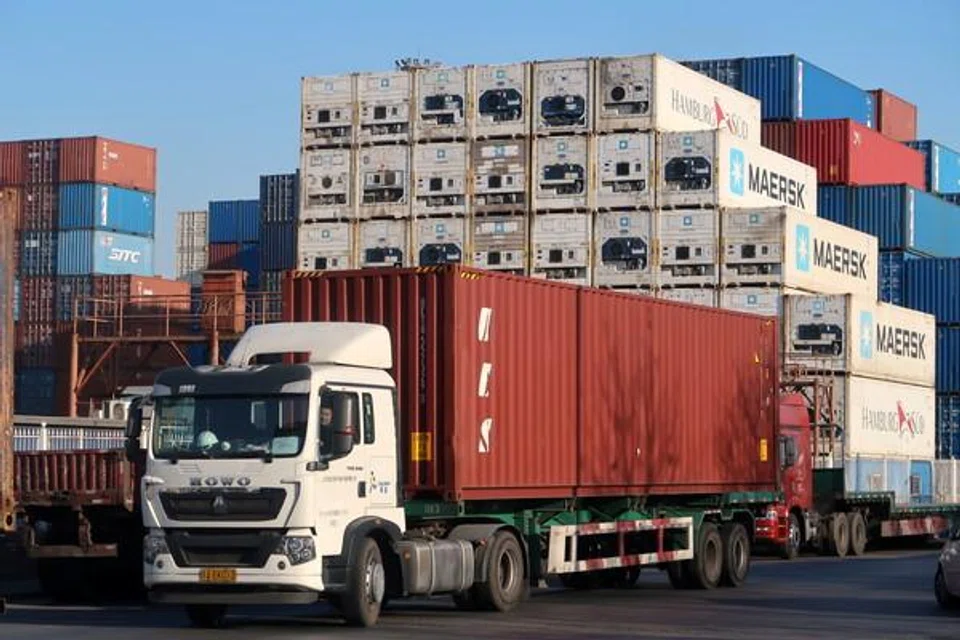
INDUSTRIAL conglomerate Hong Leong Asia will better position itself for growth by looking beyond trucking and catering to other engine sectors, chief executive Stephen Ho said in an analyst briefing on Thursday (Feb 29).
The strategic shift comes amid weaker demand in China for its powertrain solutions unit, China Yuchai International. The subsidiary primarily sells engines in the Chinese market.
Pre-Covid, the Chinese market used to move an average of 1.3 million heavy-duty trucks a year. This fell to 700,000 units in 2022, and 900,000 units last year.
Ho said: “You see some recovery, but it’s a slow recovery because business confidence is not there. Generally, people don’t want to expand on capex when they don’t have full confidence, when they’re still grappling with all kinds of issues with the economy.”
He noted that fewer trucks were running during the pandemic, which meant that the replacement rate for them also slowed. Trucks are typically replaced every six to seven years, he added.
To counter the weaker demand, chief investment officer Patrick Yau said that the company has been able to diversify its product mix to serve other markets.
For instance, demand is growing for engines for off-road usage, such as tractors used in the agricultural sector, as well as other marine and power generation use cases. Such engines make up slightly more than half of the sales volume, up from a third five years ago, he noted.
Hong Leong Asia posted a 44.7 per cent increase in net profit to S$55.8 million on a 12.4 per cent rise in revenue to S$2 billion in the second half of 2023.
Its powertrain solutions segment’s revenue climbed 12.5 per cent to S$1.6 billion, although profit after tax for the segment fell 23.4 per cent to S$28.4 million.
When asked if the company would consider disposing of its powertrain solutions segment as vehicle makers in China become more vertically-integrated, Ho said that he would not rule out the possibility.
As companies become more vertically-integrated, he pointed out that the company’s products need to be more price-competitive than those of in-house engine producers.
However, he said that by being a supplier of engines to all segments, the company is able to supply engines to a more diverse range of customers. These include Sany Group, which uses Yuchai’s parallel hybrid powertrain system in its concrete mixer trucks, as well as Liugong Tractors, which uses Yuchai’s electric hybrid continuously variable transmission powertrain.
Meanwhile, Hong Leong Asia’s building materials segment posted a 166.6 per cent increase in profit after tax to S$45.2 million, as revenue climbed 13.5 per cent to S$344.3 million.
Ho attributed this to a turnaround in Tasek, the company’s integrated cement plant and ready-mix concrete producer in Malaysia, which made a loss in FY22.
“The prices we see in Malaysia now reflect a bit more closely the higher costs of operations. I think we are at a level where profitability starts to kick in for everyone. That’s not a bad place to be,” he felt.
Ho added that, with Hong Leong Asia being the largest precaster in Singapore, he is also confident that the company’s order book will remain strong, given growing demand from the Housing and Development Board (HDB).
He explained that the requirement for half of castings for HDB units to be done locally would benefit the company as it ramps up production at its Integrated Construction and Prefabrication Hub in Punggol Barat Lane.
Shares of Hong Leong Asia closed up 1.7 per cent or S$0.01 to S$0.61 on Thursday.
TRENDING NOW
Stocks to watch: Clar, Seatrium, Sheng Siong, MPACT, NetLink NBN, Starhill Global Reit

Singapore government slaps loan curbs on individual private-hire car buyers

If Europe goes to war, the fallout will be felt in East Asia

DBS denies rumours of Indonesia unit merging with Bank Central Asia; analysts see sense in a deal

