

What's next for China's US$60t property market in 2022?
Goldman Sachs says size of sector and its intricate linkages to economy and equity market earnings make it next year's most consequential risk factor
Singapore
WHEN it comes to investing in China, patience is probably what is needed. Economists say the mainland's strict lockdown measures could drag on until the end of the first quarter of 2022. Corporate earnings could be further revised lower, but the medium-term outlook looks rosier as China places more emphasis on the quality of growth rather than quantity.
Stefan Kreuzkamp, chief investment officer of DWS, sees the wave of regulation in China and the accompanying unrest on the markets as a necessary reform, rather than a threat.
"Ultimately, the aim is to spread prosperity over more shoulders, for example, to make such elementary things as housing, education and healthcare more affordable," said the banker at Deutsche Bank AG's asset-management arm.
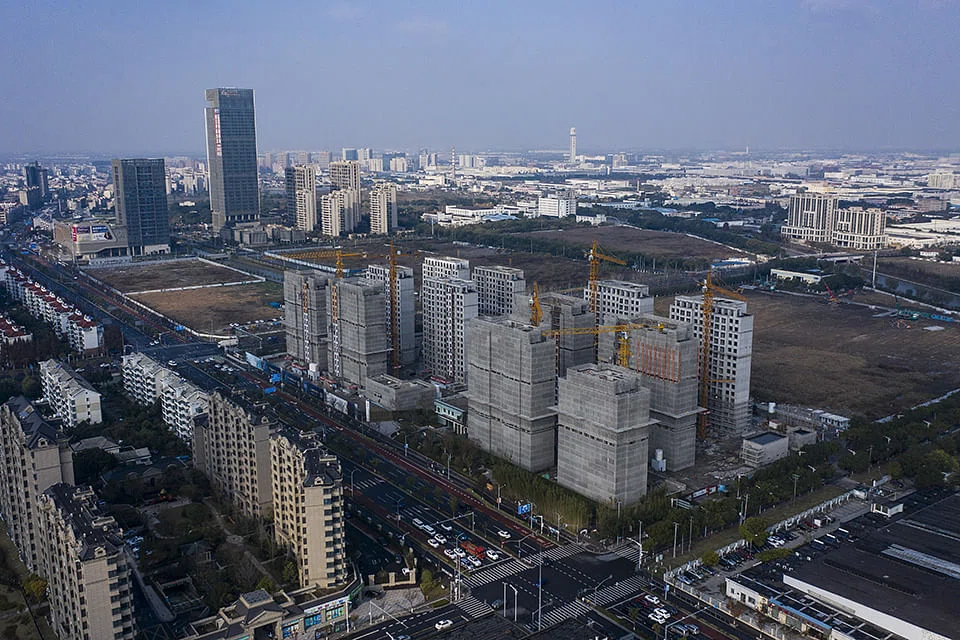
China's painful efforts to deleverage the sector last year, including setting limits on some developers' debt levels and caps on bank loans, have borne fruit. According to China Real Estate Information, a property data provider, the weighted average net debt-to-equity ratio - a key indicator of corporate debt levels - of 80 major Chinese listed developers had dropped by 4.53 percentage points year-on-year to 66.54 per cent by the end of June.
China's gross domestic product (GDP) growth is widely expected to slow below 5 per cent next year, the lowest on record outside of the crisis years, pressured by the prolonged property market deleveraging, strict Covid restrictions, normalising exports, sticky upstream inflation, and other well-telegraphed structural headwinds.
Kinger Lau, Goldman Sachs' strategist, says the significant size of the property market (estimated at US$60 trillion of notional value including inventory) and its intricate linkages to the economy (15-20 per cent of GDP or two-thirds of household asset allocation) as well as the equity market earnings (15 per cent of aggregate profits) make it the most consequential risk factor for 2022.
More regulations, or leftover policies, could be unveiled in the coming quarters as the regulatory framework takes shape, but the worst is likely to be over in terms of the regulation intensity and corresponding shocks to the market. Economists see the chance of a nationwide easing in property policies remaining low, but policy easing at local levels might continue to maintain a healthy and stable development of the property market and to protect home buyers' rights.
Lau said: "GS Research team's base case remains that while the liquidity issues at Evergrande (and other highly geared developers) may continue, the negative macro spillovers to the broader economy and financial markets should be largely contained, as policymakers have began shifting to a less-restrictive stance on the property sector since Sep."
This is based on expectations that incremental policy easing would be effective in reviving property demand and softening the growth pressures - failing which, could render significant downside risks.
Credit strategists at Goldman Sachs believe that unless the operating environment in the physical property market and credit conditions markedly improve, investors will continue to worry about tail risk in property high yield credits, especially with heavy yuan bond maturities in December this year and heavy US dollar bond maturities in January next year.
"The bumpy path ahead could sporadically instigate contagion fears in other related asset classes (China equity included) where the spillover concerns are benignly priced at present," Lau said, noting that on the bright side, index-related buying could accelerate in 2022 as the inclusion process deepens.
Shahana Mukherjee, an economist at Moody's Analytics, fears Beijing's policy moves to stem declines in home values and safeguard homeowners will have ramifications for the stability of the broader domestic financial system and eventually determine the end-impact of heightened asset price volatility on household consumption.
"If the strain persists, and in the absence of direct state-level policy support, a worsening debt situation can weigh heavily on domestic investment but can also potentially extend to impact cross-border investment flows, contingent on the industry-specific exposures to highly leveraged property developers," the economist noted.
According to Oxford Economics, China's economy will enter 2022 with weaker growth due to the property downturn and the zero-Covid tolerance approach that has impeded consumption. "Just how bad the slowdown will be and how the government will respond remain open questions," said Louis Kuijs, head of Asia economics at Oxford Economics, and Tommy Wu, its lead economist.
"We see the property downturn continuing into the first half of 2022, before anxiety over developer defaults diminishes and a modest recovery takes hold. We don't expect China to move to a Covid-containment approach until late in 2022 at the earliest, and thus project modest consumption growth," they added.
In response to the downward pressure on growth, they expect macroeconomic policy easing. "We see monetary accommodation, with ample liquidity in the interbank market and credit growth in line with the 10 per cent rise we project for end-2021, implying an increase in leverage and an improved credit impulse. We also expect an easing of property-sector policies and some relaxation of fiscal policy after the tightening in 2021, with an increase in the overall deficit."
In fact, the National Association of Financial Market Institutional Investors (NAFMII) recently gave Binjiang Real Estate, a developer which falls under the green category in Beijing's "3 red lines" the nod to issue a total of 3.5 billion yuan (S$750 million) worth of debt. DBS China analysts view the approval as a positive move for privately-owned enterprises (POEs) seeking funding.
Its optimism is also underpinned by more easing signs from local governments in China as well. On Nov 23, the government in Chengdu issued a notice, focusing on accelerating approval for pre-sales listings; relaxing restrictions on pre-sales proceeds in escrow accounts; and encouraging financial institutions to extend repayment and lower interest rates for major developers.
"This points to a more concrete signal of policy shift, which could create a material impact on developers' cash flow pressure, in our view," DBS said.
After delivering years of spectacular returns, the Chinese property market is in a multi-year slowdown. About half of the country's top 100 developers are feared unlikely to meet their annual sales quota this year.
Jeffrey Halley, senior market analyst of Asia-Pacific at Oanda, said that markets are becoming more realistic about the risks in China's property sector. Fewer investors are buying on dips in both the Chinese property stocks and debt market.
"There will always be institutional brave souls who see opportunity in distressed debt. However, they have deep pockets and the China property developer debt is not really an appropriate place for retail investors now. I still believe that there is more pain to come, both for developers and for investors still exposed to them."
Retail investors entering at current levels should be prepared for some sleepless nights, he warned.
TRENDING NOW

If Europe goes to war, the fallout will be felt in East Asia

Indonesia stocks suffer worst plunge in nearly 30 years as MSCI proposes standalone status
Director of PR firm sacked for secretly recording internal meeting loses wrongful dismissal claim
Firms linked to haze pledge cooperation in meeting with Shanmugam; government to table changes to haze law

