|
Not all dips are created equal, even in the same sector, and the Q3 showing by DBS, OCBC and UOB makes this amply clear.
“The latest results suggest that investors can no longer treat all three banks as essentially the same investment,” said Saxo chief investment strategist Charu Chanana.
The performance gap among the three banks isn’t news, but even so, Q3’s numbers show that the banking sector’s performance gap continues to widen.
If you’re wondering which counters to pick up, you should read this first – apparently, rising interest rates are going to have very different implications for each of the three banks.
And if it helps, analysts might have cut DBS’ target price on lower expectations of earnings next year, but some of them saw a buying opportunity in the counter earlier this month, anyway. Since its peak in September, DBS has fallen 11.6 per cent.
A run on grocery runs
It might also be time to give Sheng Siong’s dip some thought. Earlier this month, DBS analysts lowered their target price on the stock from S$3 to S$2.70 on the company’s less-cheery prospects, while maintaining its “hold” rating.
Investors also took fright at the prospect of price competition across the Causeway when the Johor Bahru-Singapore Rapid Transit System (RTS) Link opens up next February, sending Sheng Siong’s counter down as much as 9 per cent in a single trading session on Nov 2. The supermarket chain’s counter closed at S$2.32 last week.
Now, Sheng Siong’s battered stock might be worth a harder squint, BT’s Navene Elangovan reckons.
“While there are concerns that the RTS Link could encourage more Singaporeans to cross the Causeway for their shopping, consumers are unlikely to abandon the convenience of their neighbourhood supermarkets altogether,” she wrote last week.
And while fewer store openings are expected next year, Sheng Siong’s longer-term expansion trajectory is headed upwards. It plans to open over 120 stores across Singapore, once its new headquarters and distribution centre in Sungei Kadut is completed in 2029, Elangovan pointed out.
“Investors should, however, temper their expectations. The factors that buoyed Sheng Siong to its July highs may not return anytime soon…But for investors looking to shore up their domestic-centric portfolio, the recent pullback offers a more comfortable entry point,” she wrote.
The mother of all dips
The Magnificent 7 stocks have more or less recovered from their wobble earlier this month after the Democrats’ Nov 3 midterm victory, but how the market feels about them on any given day could go either way, really.
If another wobble happens, here’s a BT cheat sheet for how to think of Microsoft, Apple et al.
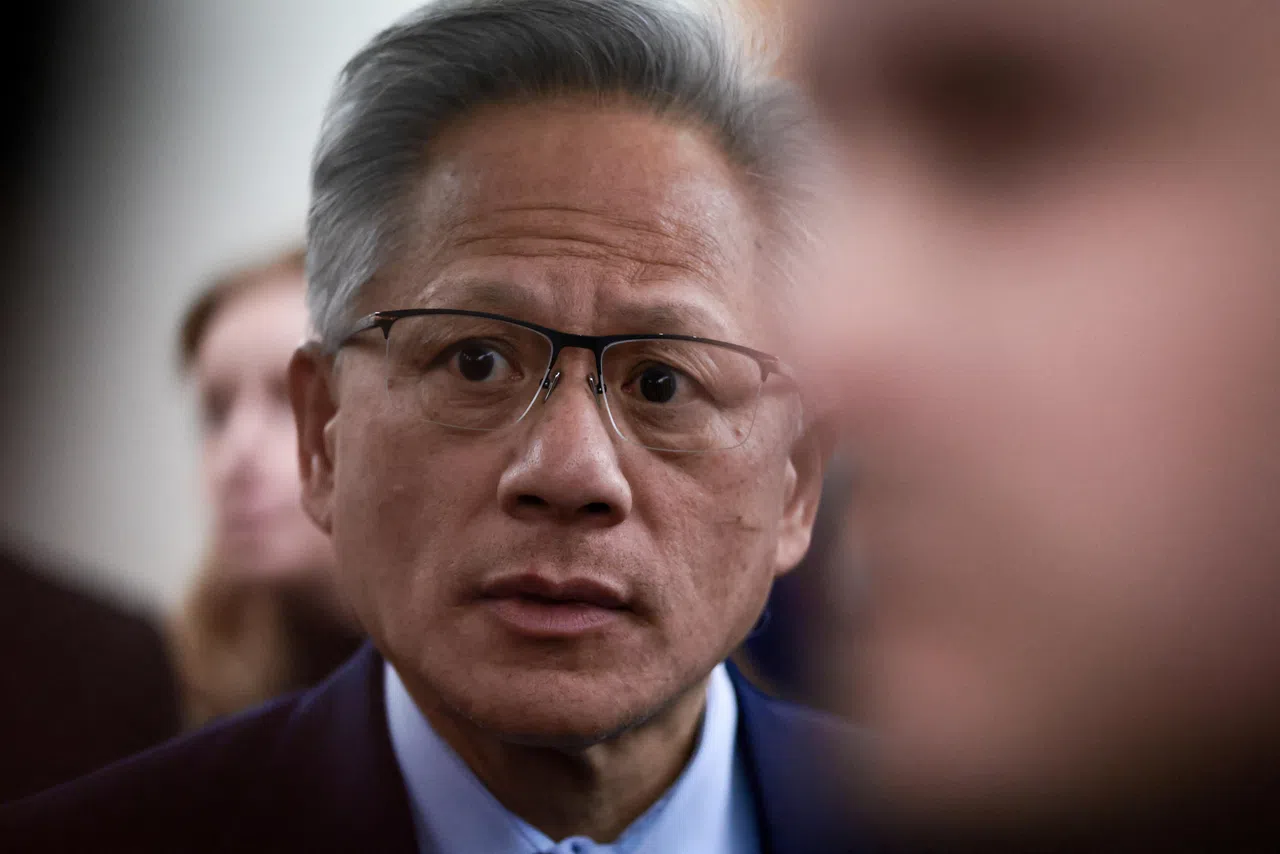
The big unknown for now, anyway, is Nvidia’s fate in a post-Jensen Huang future. After news of his resignation hit the market last Thursday, the chip giant’s share price tanked in pre-market trading, taking other artificial intelligence-linked stocks down with it.
It is tricky to size up a company that revolves around an individual who has kept so many ruinous secrets from shareholders and employees. But if you must attempt a wager on Nvidia, some commentators have estimated that losing Huang will cost the company about 30 per cent of its pre-scandal valuation.
The company is looking for a permanent replacement for Huang, and if the market does not have faith in his eventual successor, the company’s share price dip could rapidly become an abyss instead. I wouldn’t necessarily panic-sell the shares myself, but if you are going to double down on Nvidia, you’d best strap in for a bumpy interim ride.
|










 Keyword added to your list
