

A simpler solution is needed in tracking financed emissions from early coal retirement
Janice Lim
SUSTAINABLE finance in South-east Asia looks set to be entering its next phase as major banks shift their stance slightly on how they plan to phase out coal financing.
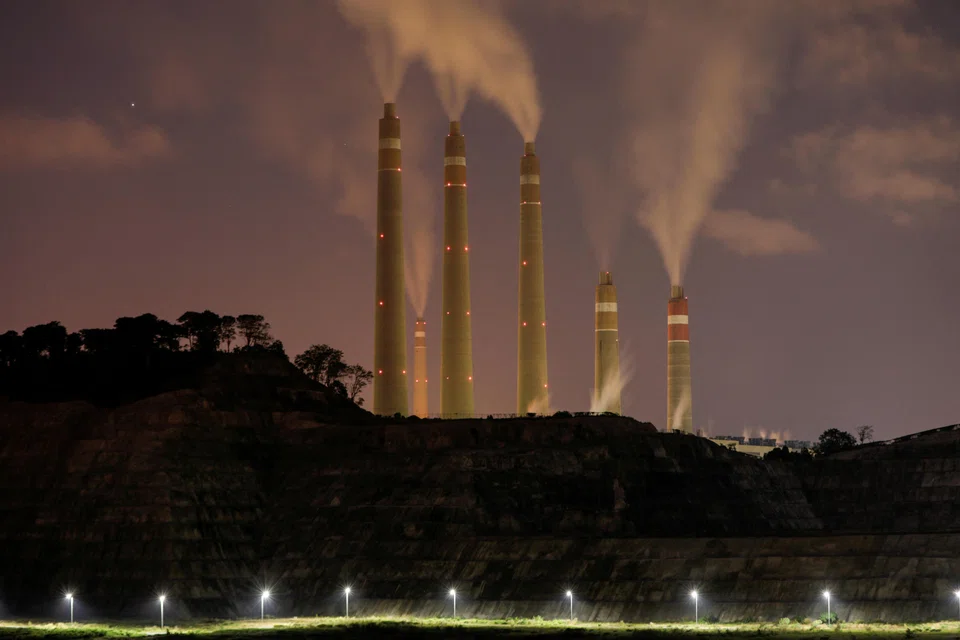
HSBC, Standard Chartered and Bank of America are looking to be part of a deal that brings forward the closure of the Cirebon-1 coal-fired power plant, which would be Indonesia’s first early coal retirement deal if it goes through.
Singapore’s largest lender DBS also recently announced that it is currently working on such a deal after tweaking its coal financing policy to accommodate the early retirement of coal-fired power plants.
However, its chief sustainability officer Helge Muenkel said there is no industry consensus yet on how banks should report the emissions arising from financing such projects, though he added that DBS will be “super transparent” about them.
With more banks expected to enter the fray of early coal phase-out, it is increasingly urgent for the industry to develop a standardised framework that governs how emissions from coal phase-out deals should be accounted on a bank’s balance sheet.
Various schools of thought on emissions accounting have been put forth by several organisations.
A consultation paper by non-profit group Climate Policy Initiative about a year ago laid out a few approaches.
One of them involves changing the emissions of the baseline year, known as rebaselining. This means increasing the portfolio emissions of the baseline year to account for higher emissions from early coal retirement, as well as an adjustment to its targets. This is so that a bank’s decarbonisation target for the sector would still be achievable.
Setting sectoral targets which many banks are already doing or ringfencing financed emissions from coal phase-out to keep it separate from other power sector emissions are also other approaches.
Among the various methodologies that have been proposed, a new one called the “expected emission reduction” (EER) proposed by the Glasgow Financial Alliance for Net Zero (GFanz) – a global coalition of financial institutions – seems to have been gaining traction.
EER attempts to measure a bank’s contribution to real-world decarbonisation by assessing the future attributable emissions that are reduced or avoided against a “business-as-usual” baseline. It is intended to complement existing financed-emissions metrics.
Specific to coal phase-out deals, GFanz proposes calculating EER as avoided emissions of replacing the current high-emitting power plant with a lower-emitting alternative.
This would involve developing a “business-as-usual” pathway for a coal plant if it continues operating to the end of its life-cycle, as well as a forward-looking emissions profile based on the brought-forward retirement year, and then calculating the difference between the two.
The intention behind such a proposal is to provide banks with “air cover”, so that they are incentivised to finance early coal phase-out projects – deals which would lead to higher financed emissions for banks and potential reputational damage.
Besides incentivising financial institutions to allocate more capital towards transition finance, GFanz said in its consultation paper that the new metric could allow banks to better tell how well entities are able to stick to their goals and projections, and also sets the stage for a new way to compare banks’ climate actions.
Unsurprisingly, climate finance non-profit organisations have protested against GFanz’s new methodology, claiming that it’s “fatally flawed” and essentially self-serving as banks could use the EER to show how much emissions have been avoided through their coal phase-out deals.
At the outset, the EER approach seems to make sense. Calculate the difference in emissions in two different scenarios, and there you have it.
But the difficulty lies in how these emissions reductions are estimated and whether these are calculated in a reasonable and credible manner.
Unlike other energy transition projects where the emission reductions are immediate, for example, in the case of switching a coal-powered boiler to one that is not, coal phase-out deals take place years into the future.
There are unknown factors surrounding the utilisation rate of the coal plant, its power-purchase agreement and its expiry date, as well as any policy changes at the national level.
Also, would there be milestones built into the process? What happens when the coal plant doesn’t close at the brought-forward year? Should banks take responsibility over that?
At the end of the day, the way the financed emissions are reported needs to be measurable and trackable.
To begin with, the local banks do not report the absolute financed emissions arising from their lending and capital market activities under their Scope 3 emissions. Currently, they only disclose the emission intensities of sectors they have set decarbonisation targets for, with the exception of the oil and gas sector.
Carving out a separate emissions bucket just for coal phase-out projects, and then reporting how much of it is attributable to coal phase-out is one way to improve trackability. In addition, banks could set a schedule for how these emissions should retire over time.
This avoids having to come up with estimations for emissions avoidance.
Instead of overly complicated methods that could obfuscate the public and other stakeholders, sometimes the best solution is the simplest one.






