

E-wallet fintechs prosper in the Philippines by targeting the unbanked
Covid-19 restrictions forced many people to adopt digital solutions, just as companies started offering cheaper financial products
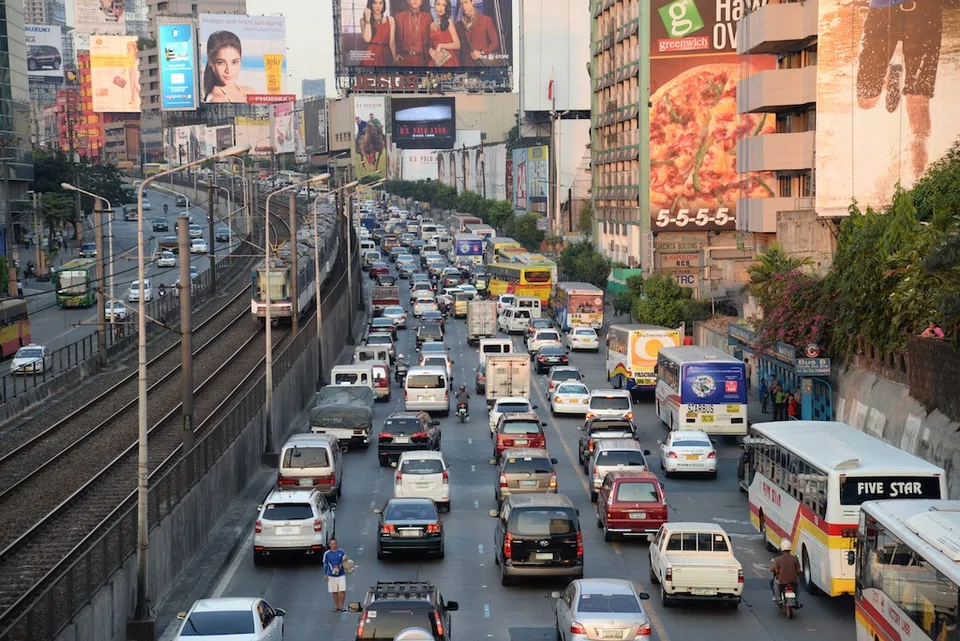
SINGAPORE’S well-capitalised digital banks have made a splash lately with targeted offerings to wrest market share from the incumbents. The real change, however, is taking place with much less aplomb across South-east Asia – where niche fintechs are finding a newly receptive audience for their digital products.
In the Philippines, bank account ownership has almost doubled over the last two years – rising to 56 per cent in 2021 from 29 per cent in 2019 – going by the findings of the biennial Financial Inclusion Survey for 2021 by the Philippine central bank, Bangko Sentral ng Pilipinas (BSP).
Account openings were driven, in part, by movement restrictions during the Covid-19 pandemic, which forced people to make transactions online. This behaviour has stuck with users, even as the pandemic has eased, said Maybank analyst Rachelleen Rodriguez.
“People have figured out that it’s easier to make transactions online, and the banks have been very active in marketing their digital platforms, so we really saw an uptick in the usage of digital banking apps,” she said.
BSP has also been working to raise digital adoption and financial inclusion by offering regulatory and policy support to players offering cheaper or innovative products and solutions. Its targets are to have half of all transactions digital, and 70 per cent of Filipino adults to have formal banking accounts by 2023.
During the pandemic, the Philippine government started distributing social security benefits electronically instead of in cash. This encouraged people to open a bank account to receive the benefits, said Anosh Pardiwalla, principal at consultancy Oliver Wyman.
E-wallet players have been the biggest beneficiaries of the country’s digital banking push, Rodriguez said. The largest e-wallet operator in the Philippines, GCash, had 66 million users as at the end of June – in a country with a population of around 110 million.
GCash is owned by Mynt, a fintech startup which counts Singtel associate Globe Telecom and Alibaba affiliate Ant among its shareholders.
Most of the bank accounts in the Philippines are e-money accounts, BSP said. A significant number of account holders use their accounts for payment-related transactions rather than for savings. These transactions include receiving remittances, salaries and financial assistance and making cashless payments.
This is a reversal from 2019, when savings exceeded payment transactions.
Maybank’s Rodriguez also noted that a sizeable portion of transaction volume is coming from merchants that turned to digital payments amid the pandemic. In the first half of 2022, GCash registered 5.2 million merchants and social sellers. It also registered 520 merchant partners for GLife, an app that combines various merchants and brands’ mini apps into a single page within the GCash dashboard.
Targeting the underserved
Unlike the digital banking arms of the larger banks, which are targeting the more affluent customers to avoid credit risks, e-wallet players in the Philippines are targeting those without large bank balances, Rodriguez said. They are also offering shorter loan durations.
“We believe that digital banks and traditional banks can co-exist in the current environment and can still grow the market,” Rodriguez said.
Oliver Wyman’s Pardiwalla, too, said traditional banks do not pay a lot of attention to the less-affluent segments as these are not as profitable. This situation could, however, change with the introduction of new technologies.
He said: “Traditional banks have the legacy costs still piled up, so they’re not replacing it overnight with new technology. It’s the question of, in the long term, if they want to target this last segment.”
These e-wallet players are also emerging as important sources of funding for individuals, as well as micro, small and medium enterprises (MSMEs).
BSP’s report said that banks rank second from the bottom, just above pawnshops, as a formal credit source.
Sanjay Uppal, founder and chief executive of credit modelling platform Finbots.ai, said: “Due to limited traditional and transactional data, many lenders end up rejecting more loan applications than they approve.
“Many lenders and financial institutions we speak with actually have a lot of data, but are not able to do much with it because of outdated infrastructure or capability challenges.”
Challenges for digital banks
Industry watchers say there is much to do for BSP to reach its targets.
Maybank’s Rodriguez noted that financial literacy and the understanding of various banking products is still low in the country, even though the BSP has been trying to educate the public through roadshows.
Internet connectivity is also an issue for those living in rural areas, Oliver Wyman’s Pardiwalla said.
“So you need to make sure what you’re providing is a very light model, rather than something that’s going to consume too much bandwidth,” he said.
Tan Bin Ru, South-east Asia chief executive at digital banking solutions provider OneConnect Financial Technology, noted that the lack of a national identification system also makes it difficult for banks to implement a know-your-customer solution.
Traditional banks in the Philippines allow customers to open a basic deposit account with hardly any official documents. But awareness of such accounts is also low, said BSP, especially in rural areas.
Yet, the low levels of banking penetration suggest plenty of potential.
OneConnect’s Tan said competition is strong in the Philippines as new digital banking licences are being given out. She also expects the ecosystem to be supported by GDP growth and recovery from the pandemic.
TRENDING NOW

Malaysian king buys stake in Singapore-listed mining firm expanding into rare earths
Family offices ‘kept captive’ by relationship managers turn to independent advisers, direct deals

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Could stablecoins be the future of money?

