CDL net profit drops 75% to S$317.3 million for 2023, targets S$1 billion in divestments
Samuel Oh &
Mia Pei
CITY Developments Ltd’s (CDL) net profit dropped 75 per cent to S$317.3 million in 2023, as higher financing costs ate into profits in the absence of divestment gains.
This translate to an earnings per share (EPS) of S$0.336, against that of S$1.403 in the previous corresponding year.
Shares of CDL fell 3.2 per cent on Wednesday (Feb 28) morning, losing S$0.19 to touch a five-year low at S$5.77 at 10.12 am with 3.1 million shares changing hands. The counter ended the day at S$5.78, down S$0.18.
The property group posted a 50 per cent rise in revenue to a record S$4.9 billion for the year ended Dec 31, 2023, driven by its property development segment. But it missed analysts’ earnings estimates, which averaged S$358 million in forecasts compiled by Bloomberg.
CDL said that its net finance costs doubled and eroded profits last year. Average borrowing cost rose to 4.3 per cent per annum, up from 2.4 per cent in FY2022. It expects rate cuts before the end of this year will help alleviate its burden.
Net gearing ratio rose to 61 per cent last year, from 51 per cent in FY2022, largely due to the S$2.4 billion in acquisitions CDL completed and paid out in 2023.
CDL spent close to S$1.3 billion acquiring two residential development sites in Singapore in Woodlands and Toa Payoh, and another S$891 million buying assets in the UK.
As at Dec 31, 2023, cash reserves stood at S$2.2 billion, with cash and available credit totalling S$3.6 billion.
For the six months to Dec 31, net profit rose 51.2 per cent to S$250.8 million on the back of a 22.9 per cent increase in revenue to S$2.2 billion. Half-year EPS climbed to S$0.27 from S$0.176 previously.
A final dividend of S$0.08 per share was proposed for the second half-year, bringing the total dividend for 2023 to S$0.12 per share and dividend payout ratio to 36 per cent.
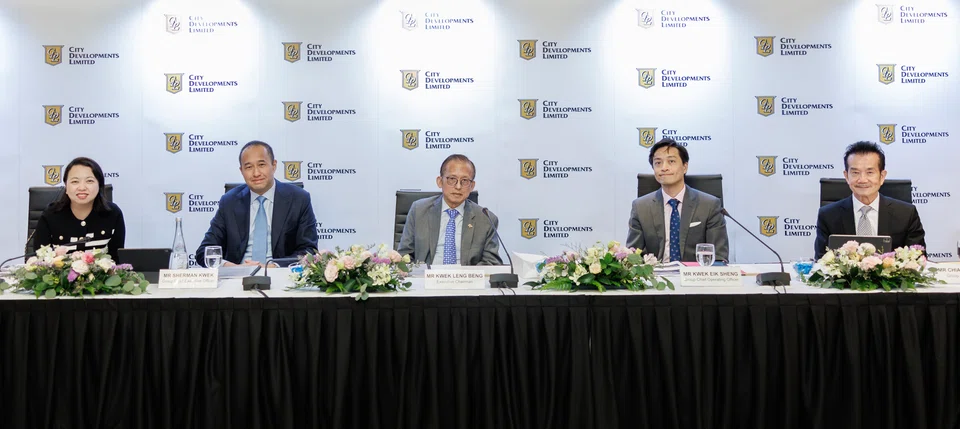
In the company’s earnings briefing on Wednesday, chief executive officer Sherman Kwek said that CDL was targeting divestments of S$1 billion this year.
Vijay Natarajan, vice-president for equity research at RHB Singapore, said: “The core earnings of CDL missed our estimates on weak margins and higher financing costs. We see CDL’s announcement of higher divestments this year (target S$1 billion) as beneficial for lowering the debt burden as well as unlocking value, with the stock trading at a deep discount to book value and revised net asset value.”
Kwek Leng Beng, CDL executive chairman, said that the group “delivered a resilient set of results despite an extremely challenging year for the global real estate sector, with a high-interest-rate environment, inflation, weak global economies and geopolitical tensions”. He added: “Singapore’s additional property cooling measures added to the challenges.”
Revenue from property development rose, largely due to its sold-out executive condominium project Piermont Grand at Sumang Walk; and the divestment of a freehold site in Shirokane, Japan for about 50 billion yen (S$495 million). Profit before tax recognised for Piermont Grand came in at S$121 million, while the sale of the Shirokane plot yielded S$155 million, boosting development profits. But its Singapore project sales fell in a year when government cooling measures led to a slowdown in home sales.
CDL sold 730 residential units in 2023, some 50.9 per cent less than the 1,487 units it sold in the year before. Sales value fell 48.6 per cent to S$1.5 billion, down from S$2.9 billion in 2022.
The group’s Tembusu Grand project has sold 60 per cent of its 638 units as at Feb 25, while The Myst has sold 51 per cent of its 408 units. Haus on Handy, Amber Park and Piccadilly Grand were fully sold, it added.
The developer will launch two residential projects in H2 2024: a 348-unit development at Champions Way in Woodlands, and Union Square Residences in Clarke Quay, with an estimated 366 units. Also in the pipeline are the 246-unit freehold Newport Residences in Anson Road and the Toa Payoh project.
CDL will focus on strategic site acquisitions in 2024 to build its pipeline, the company said. CEO Kwek noted that tenders for “good sites” are “furiously competitive”, and the Additional Buyers’ Stamp Duty which affects foreign purchasing and high financing costs are not helping.
Hotel operations recovered strongly, with revenue per available room (RevPar) for FY2023 up 25.3 per cent to S$168.7 and strong growth in Asia and New Zealand.
Singapore and the UK reported RevPar growth of 19.9 per cent and 10.6 per cent respectively, while the rest of Asia outperformed with 77.2 per cent improvement, driven by hotels in China and Taiwan.
Investment portfolio revenue increased due to contributions from recently acquired assets – St Katharine Docks and six student accommodation properties in the UK. “The office sector in the UK is going through some rumblings because of high interest rates, but nowhere near the US office sector which is going through a shake out,” said Kwek.
He remains bullish on purpose-built student accommodation in the UK, as well as the private rented sector in Japan, Australia and the UK, as housing prices remain high in these regions.
CDL’s assets in these sectors may be put into private equity funds or a real estate investment trust platform in Japan or regional markets, when they have grown in scale, said Kwek. “But this will depend on investors’ appetite.”
CDL said that its Singapore portfolio stood resilient, with offices 97.1 per cent committed (out of net leasable area, or NLA, of 1.5 million square feet), and its retail space spaces 97.6 per cent committed (of NLA of 800,000 sq ft).