

Changes to SGX restructuring framework are an upgrade – for judicial managers
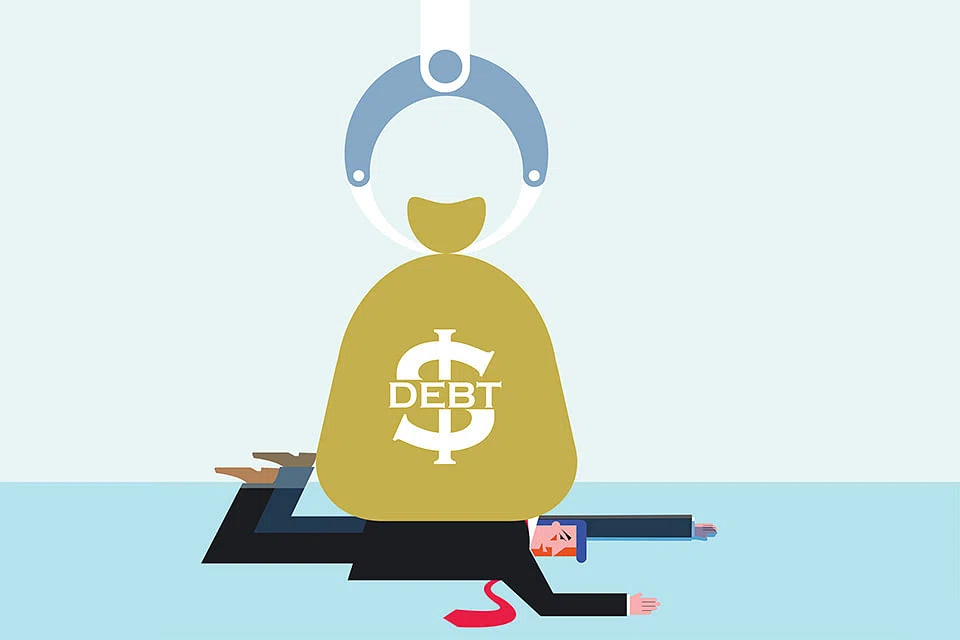
IF TAYLOR Swift had to perform in a school hall with poor acoustics and a decades-old sound system, would she still sound as good?
A Swiftie – what her fans call themselves – would answer “yes”.
Talent performs better with quality tools, but can work wonders even without it.
Let’s apply this analogy to the corporate world, assuming corporate leaders are the musicians and shareholder returns the profits from making music.
The venue and sound system might be represented by economic environments and regulatory regimes. Assuming these two elements are equal for all companies, why do some fail even as others succeed?
There are many reasons, of course, but nearly all of them come down to one thing: the ability to make good decisions.
You, dear reader, might argue that this is just stating the obvious. Yet, market players consistently expect regulatory upgrades to lead to performance improvements without factoring in who is performing.
Consider the recently proposed enhancements to the corporate restructuring framework.
The Singapore Exchange (SGX) aims to help issuers restructure more efficiently by aligning its rules with Singapore’s Insolvency, Restructuring and Dissolution Act 2018 (IRDA).
“(The) IRDA aims to smoothen and speed up the restructuring of financially distressed companies. This may increase the chances of white knight rescues and trading resumptions. These outcomes, if they materialise, will be of more value to shareholders than years of proceedings that will further deplete distressed companies’ scarce finances,” said Tan Boon Gin, chief executive of SGX Regulation (SGX RegCo), in a news release last week.
The Business Times reported generally positive responses from industry players to the news, although there was also some concern that power might shift slightly from shareholders to creditors.
Among the most significant of the proposed changes is one removing the need for shareholder approval if a judicial manager or liquidator needs to sell a major asset.
An ailing company’s most valuable asset would also be its most viable asset. A judicial manager might choose to sell this asset, raising enough money to repay creditors, while shareholders might prefer the restructured company to be built around this viable asset.
SGX RegCo argued in its consultation paper that judicial managers “have a duty established by case law” to obtain a “proper” price for assets.
The paper also noted that “relief is available under the IRDA for shareholders if judicial managers managed a company’s affairs, business and property in a manner that was unfairly prejudicial to the interests of the shareholders”.
In other words, shareholders need not worry that they will be stiffed by the judicial management process.
Is this assurance enough for market participants? SGX RegCo has invited responses to its proposals, and market participants should take the opportunity to do so – particularly those who are concerned about that power shift.
At the same time, these proposed enhancements need to be recognised for what they can and cannot accomplish – as well as what they are meant to achieve.
The restructuring framework exists to support companies in poor health. Their managers made bad choices, and would either have left or are on their way out.
To return to our musical analogy, the musicians are now the judicial managers – performing in a crummy venue for a diminished audience.
Enhancing the restructuring framework only gives the judicial managers better tools. It won’t help them pack a stadium.
TRENDING NOW

Prima to move out of historic Keppel Road flour mill building in 2028
Temasek-related Azalea, SeaTown, Seviora Capital to merge in 2027
Family offices see more tailored products, leverage ‘collective firepower’ for direct deal access
Singapore room rates soar, but hotels seeing mixed demand from F1 race and events

