

Geopolitics is driving Asean bank digitalisation
Transition to the cloud comes at a good time for regional banks
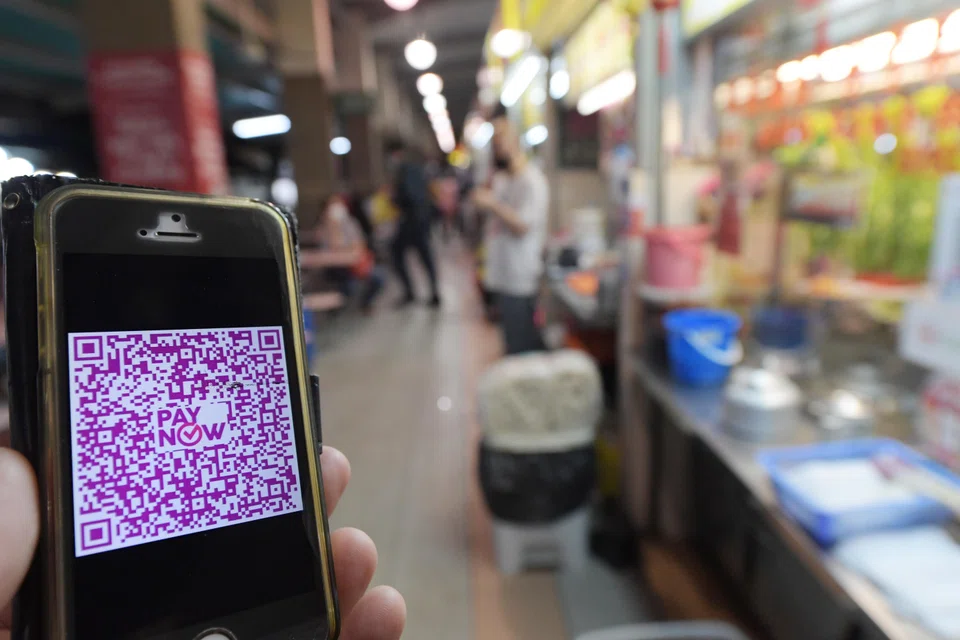
IT IS no secret that super-apps and other fintechs have taken a bite out of banking’s core business in South-east Asia. Leveraging popular shopping or delivery services has allowed them to expand from singular types of transactions into all kinds of financial services. The trend has made digital wallets central to regional spending.
But at the end of March, the Asean Finance and Central Bank Deputies Meeting also put an economic-security spotlight on digital transactions.
Asean’s financial leaders have called for greater reliance on local currencies, and that implies accelerating digitalisation for regional banks. The kind of instantaneous cross-border settlement that the March meetings outlined means regional banks will need to shift more operations into the cloud. Legacy systems can’t do the job.
That might look like it will compound the already challenging task of digital transformation for regional banks, but it could be just what they need.
Financial institutions in South-east Asia should embrace this opportunity to update their capabilities so that they can meet policymakers’ expectations and the broader economy’s needs.
Grasping the moment comes down to digital savvy and software as a service (SaaS).
Rising digital pressure
Digital wallets are already at the core of Asean spending – online, at service points, and increasingly across borders. Smartphone ownership created demand and the pandemic accelerated adoption. That has enabled super-apps to tap the region’s large unbanked and under-banked populations, capturing a large share of consumer activity.
Other businesses have taken note, launching digital banks. Singtel teamed up with Grab in 2022 to create GXS Bank. And in March, Sea Group, the parent of Singapore’s top e-commerce and e-sports platforms, launched MariBank.
Now the region’s governments are raising the stakes.
As Asean’s finance ministers discussed financial resilience, safeguarding against global risks – ranging from pandemics to inflation – came into focus. The possibility of contagion from recent bank failures in other regions was a natural concern, as was growing geopolitical tension between the West and China, and its potential implications for the dollar-based global financial system.
The bottom line from Asean’s financial leaders is a need to reduce dependence on foreign currencies, and boost local currency use for regional settlements. The objective is to expand existing local currency transaction agreements and enable a cross-border digital payment system for Asean.
Now, it’s not just consumers who want digital wallets, it’s whole nations.
From pressure to inevitability
The push is already underway. Last summer, Bank Indonesia and the Monetary Authority of Singapore announced cross-border QR payment links. This February, Singapore linked to India’s payment system. People in either nation can use their local platform to pay someone on the other with instant mobile phone transfers that bypass bank branches and strip away bank transfer fees.
For banks, that may sound like a challenge, but the opportunity is to accelerate their transformation and focus on digital wallets, integrated services and real-time payments by replacing legacy tech stacks with cloud-based applications. Consumer demand has already catalysed this process, but geopolitics and policy will speed it up.
Deeper into digitalisation
SaaS means running enterprise applications over the Internet, or in the cloud, rather than on localised computer hardware. If banks leverage the benefits of this model, they have a better shot at keeping up with consumers’ digital trajectories.
The mobility, speed and flexibility of cloud applications are the strength that fintech challengers once commanded; now it’s a baseline expectation even at the central bank level.
South-east Asia’s regional banks can play – and win – at this game too.
If the new backbone for Asean’s interbank activity is digital, then regional banks can also take advantage of the wealth of capabilities accessible via application programming interfaces (APIs) that are already available through SaaS. Cloud technology means a step change in customer service.
It means accessibility to modern systems to verify identity and automate and improve cybersecurity, or aggregation of accounts, so consumers can view all finances in one place, including across asset types or currencies. APIs let banks choose services from third-party developers so that new offerings, such as buy-now-pay-later, become almost as quick and straightforward as putting a new app on your smartphone (that’s a simplification, but not by much when compared to the challenge of adding new features to legacy banking systems).
And because APIs can provide for easier interaction with customer data and devices, basic transactions offer better customisation and market insights, turning payments into engagement tools. And that can be extended across a wider ecosystem of service partners.
Transition to the cloud comes at a good time for regional banks. Public equity markets have become less interested in hyper growth, as with super-apps, and more interested in solid profits.
Regional banks are generally in good financial health, putting them in a good position to build the next generation of financial infrastructure. And while deploying SaaS still requires investment, the technical expertise behind it is far easier and cheaper to come by than new customers in a hyper-competitive arena.
Consumer trends may have made digital wallets competitive with banks. But geopolitics could transform banks into the ultimate wallet. SaaS makes that possible: banks just need to seize the moment.
The writer is co-founder and CEO of Episode Six, a payments technology company.






