

Singapore-grown expertise anchors ComfortDelGro as it ramps up overseas operations
Derryn Wong
TRANSPORT giant ComfortDelGro (CDG) is plotting a course for growth by increasing its footprint overseas and venturing into adjacent businesses, but it is a strategy that will continue to be anchored by its operations in Singapore.
Over the past 12 months, CDG has made notable moves abroad.
In 2023, it announced the proposed acquisition of Australian taxi operator A2B for A$165.1 million (S$145.7 million). In February this year, it acquired CMAC Group, a UK-based ground-transport management and accommodation network specialist, for £80.2 million (S$135.4 million). (*see amendment note)
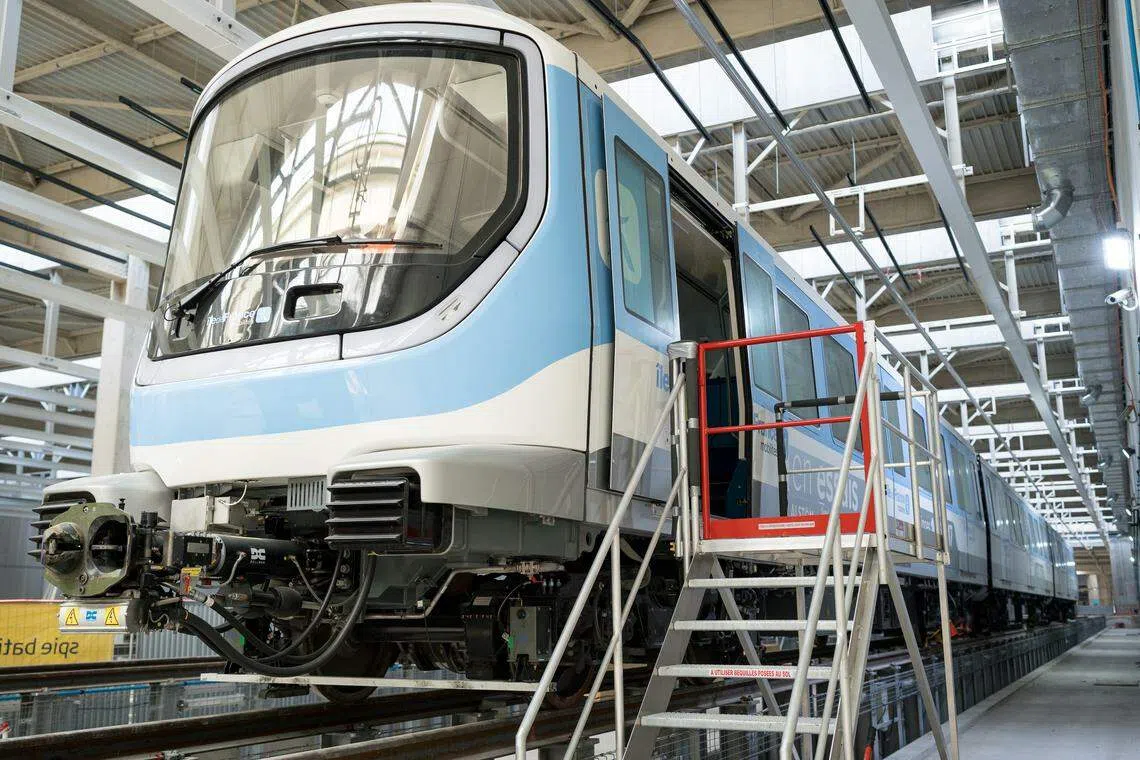
Through joint ventures with foreign partners, it has also secured an 11-year contract to operate and maintain the Stockholm Metro, as well as a six-year contract for a metro line in Paris.
Cheng Siak Kian, the managing director and group chief executive officer of CDG, told The Business Times that the group’s two key pillars will remain the taxi/private hire and public transport (which includes rail and bus) segments.
“We don’t have a specific target (for overseas earnings), but clearly the overseas proportion will continue to grow,” he said.
As at end-December 2023, 42.7 per cent of CDG’s revenue and 26 per cent of its operating profit came from outside Singapore.
Cheng said that this will vary in the future, as “a lot more earnings will be generated from overseas business, because that’s where the market is bigger”.
Its overseas rail ventures, such as the Stockholm Metro, would add to earnings but not the company’s top line as CDG is not a majority shareholder, he said.
Blessed with a generous war chest
The company certainly has the funds to keep growing inorganically. As at end-December, its cash and cash equivalents rang in at S$856.9 million, despite a drop of 11.4 per cent year on year.
“I think we have been blessed that when I took over, the balance sheet (was) very strong, and that has allowed us to grow the business through acquisitions,” said Cheng, who began his role on Jan 1, 2023, succeeding Yang Ban Seng.
“We’ve overcome some of the comments from our investors that we have a ‘lazy’ balance sheet, with a little bit too much (cash).”
The deployment of the company’s war chest in acquisitions has been in a “very deliberate, very disciplined” manner, he said, adding that CDG closely examines whether such investments would be sustainable, how they would fit into its overall strategy, and how they would bring the best value to its shareholders.
While acquiring A2B is an instance of CDG expanding its taxi/private hire segment overseas, the CMAC purchase is a more “creative” move.
CMAC, which is a platform that helps airlines move passengers from airports to hotels, is one example of an adjacent business that will add growth to CDG, since it would be able to harness the group’s existing taxi and bus operations in the UK, said Cheng.
Singapore skills, different places
Cheng said that the company has continued to make in-roads in winning overseas rail tenders, which has been informed by its success in running rail projects at home.
In 2022, CDG commenced operation of New Zealand’s largest rail network, the Auckland Rail Franchise, through Auckland One Rail, a 50:50 joint venture with Australian rail operator and maintenance company UGL Rail Services.
The eight-year contract was valued at S$1.13 billion. It was also the first overseas heavy-rail venture by a Singaporean company.
Both the Swedish and French rail tenders represent new markets for CDG, and they are also operated as joint ventures with foreign partners. The Swedish tender is the company’s largest rail project outside of Singapore to date.
Cheng said that CDG’s value-add for its partners is its experience in the operation and maintenance of fully automated rail systems, especially in the area of building reliability, which it has gained from 20 years of running the North-East Line in Singapore.
“A lot of the expertise we generated, and a lot of our references are actually based on the fact that we have done well in Singapore,” he said.
“When clients around the world look at Singapore, they do see us as representing (Singapore’s excellence), so they expect us to bring that customer experience, reliability and innovation, and to share those with them as well.”
For the full year ended December, CDG posted a net profit of S$180.5 million, up 4.3 per cent from S$173.1 million in FY22. Full-year revenue rose 2.6 per cent to S$3.9 billion.
The group’s steady performance has not gone unnoticed by investors.
CDG generated total returns of 20.6 per cent in 2023. In comparison, the benchmark Straits Times Index (STI) returned 4.7 per cent over the same period.
So far this year, the stock has fallen 2.9 per cent but still outperformed the STI, which declined 3.3 per cent.
Out of nine analyst recommendations, the counter has eight “buy” ratings and one “hold” call.
RHB, for example, has a target price of S$1.60 on the stock, representing a 17.6 per cent upside to CDG’s closing price of S$1.36 on Mar 1.
RHB analyst Shekhar Jaiswal said in a recent report: “(CDG) should continue to see growth in 2024, aided by overseas public transport earnings; Singapore rail ridership staying robust; and strong taxi earnings amid the increase in fares and commission rates; as well as the introduction of a new fee for bookings on the Zig platform.”
While the group seeks overseas expansion, Cheng said that Singapore remains a “very important” market for the company, having bidded “very competitively and very strongly” for the upcoming Jurong Region and Cross Island lines.
Singapore is still “the home base that we want”, said Cheng, adding that the group will continue to be anchored in Singapore.
“Our clients see that formula, or (standard operating procedures) that we have in Singapore, which can be used overseas. That forms the base for us, and will continue to be critical for us.”
*Amendment note: An earlier version of the story stated that CDG had acquired Australian taxi operator A2B. The article has been amended to reflect that the proposed acquisition of A2B has not yet been completed.






