Stock markets are driving a new American century
The US’ growing financial dominance may be making up for its declining influence in other realms
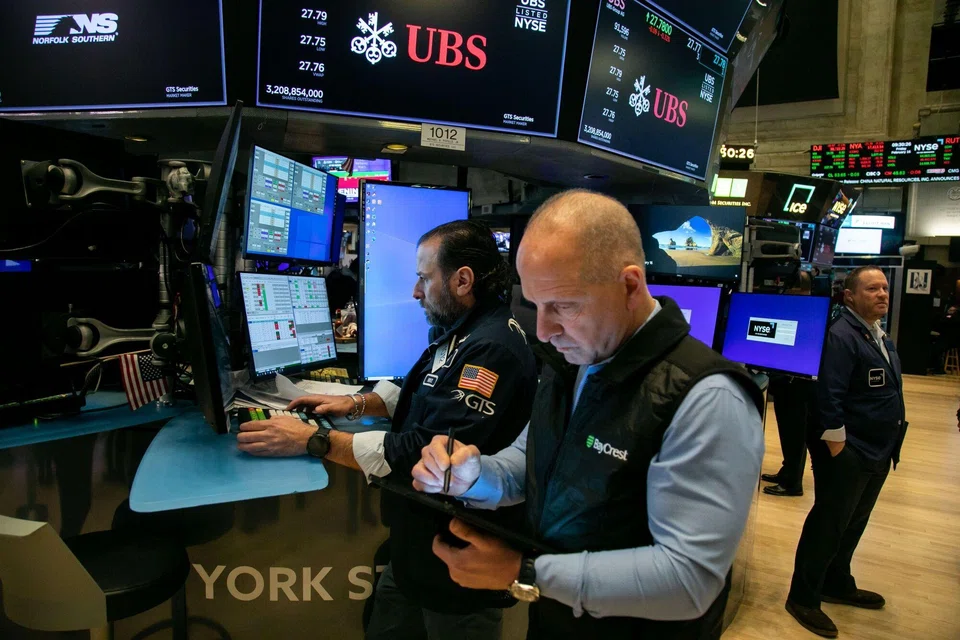
THE worldwide dominance of US equities is increasingly obvious. Of the top 10 components of the MSCI global stocks index – which itself now consists of about 70 per cent US stocks – eight are US technology companies. The S&P 500 has breached the 5,000 level. On most days, Apple or Microsoft alone is more valuable than the entire stock markets of major European countries. By one estimate, publicly traded US firms accounted for 44.9 per cent of global market capitalisation last year.
All these gaudy numbers raise a question: Is the world on the cusp of a new American century, at least in the corporate realm? The answer is a qualified “yes”.
One reason why US equities are gaining in relative terms is that the Chinese stock market has been crashing. China’s stock market has not traditionally been very representative of the broader Chinese economy, but this decline in equities coincides with broader economic troubles: a burst real estate bubble, local government debt problems, and high youth unemployment. The risk is rising that China’s economic future lies with state-owned enterprises, rather than private capital.
A related issue is that the European Union has not yet rebounded into steady economic growth, whereas the United States’ economy remains strong. It is hard to say how much that reality influences particular share prices, but it does not hurt the relative prospects of US equity markets.
A further reason for the US success: the rise of tech as an economic force. The most profitable tech companies tend to be very large, usually because the software can be readily scaled, or (as in the case of Apple, for example) the supply chain is difficult to replicate. Most of the very large global tech companies were started in the US – which is their natural Western home, given the tech regulations and market fragmentations of the EU. Innovations in artificial intelligence (AI) may cause US tech companies to rise all the more.
And over time, pharmaceutical companies might be expected to become more like tech companies, as they explore computational and synthetic biology. Nor is it difficult to imagine some large educational companies arising, as tech innovation could spur growth in this field.
And, if investors see tech as continuing to rise in importance, that will favour even more value concentration in US public markets. To understand why, consider electric utilities, which often have national roots. To the extent electric utilities rise in importance, that will strengthen various national equity markets but not the US market overall. At the moment, however, tech seems poised for stronger growth than do the more localised economic sectors – favouring the predominance of US equity markets.
The major US tech companies sell to the entire world. Therefore, part of the relative rise of US equities is about the liquidity and prestige of US markets, not just US economic success. US listings will dominate, and all the more over time, even when US customers are not the main source of revenue. Say you found a successful French AI company. Wouldn’t you prefer to be listed on the Nasdaq rather than on the Paris stock exchange? A Nasdaq listing may make it easier to raise money, and the rest of the world will have a better understanding of the rules under which your securities are governed.
There is thus a self-reinforcing liquidity effect favouring the dominant market for equities. That is one version of a new American century, and it does not require US-based companies to do all the heavy lifting. Nonetheless, the major companies of the world will play by America’s rules, and continue to court its favour.
The biggest challenge to the dominance of the US equity market likely will come from China in growing sectors such as electric vehicles and solar panels. Still, China is more likely to end up as a separate, somewhat segmented, set of equity markets, rather than a true global rival to the US.
And, just to fill out this rosy picture of America’s economic future, the US is doing well in other kinds of financial markets as well, including venture capital, private equity and private credit. The financialisation of an economy does carry risks, but a lot of the recent developments are about deleveraging and greater maturity-matching – which should contribute to stability rather than damage it.
Of course, in many ways America’s global influence is in decline. So maybe it is unseemly, if not inappropriate, for the US to celebrate its increasing global financial dominance too loudly. At the very least, however, a cautious and self-critical American pride is called for. If only we could bottle that and sell shares in it, too.