Beyond Nvidia: How Singapore is earning its place in the semiconductor value chain
It occupies the part which AI has made expensive to get wrong – this is starting to be reflected by the listed market
 Add BT as a preferred source
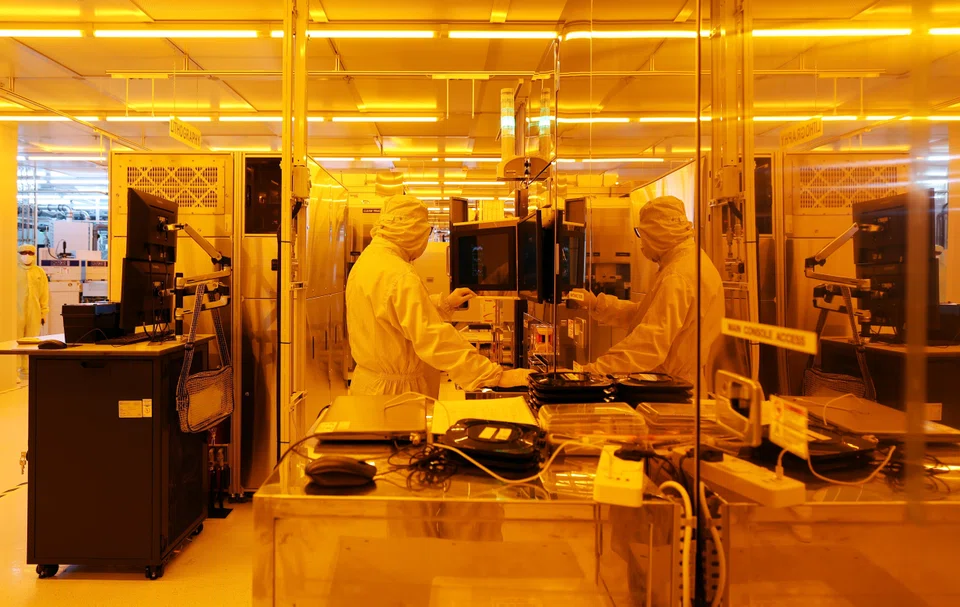
[SINGAPORE] Drive out to Tampines and you can see a decade of decisions in one district.
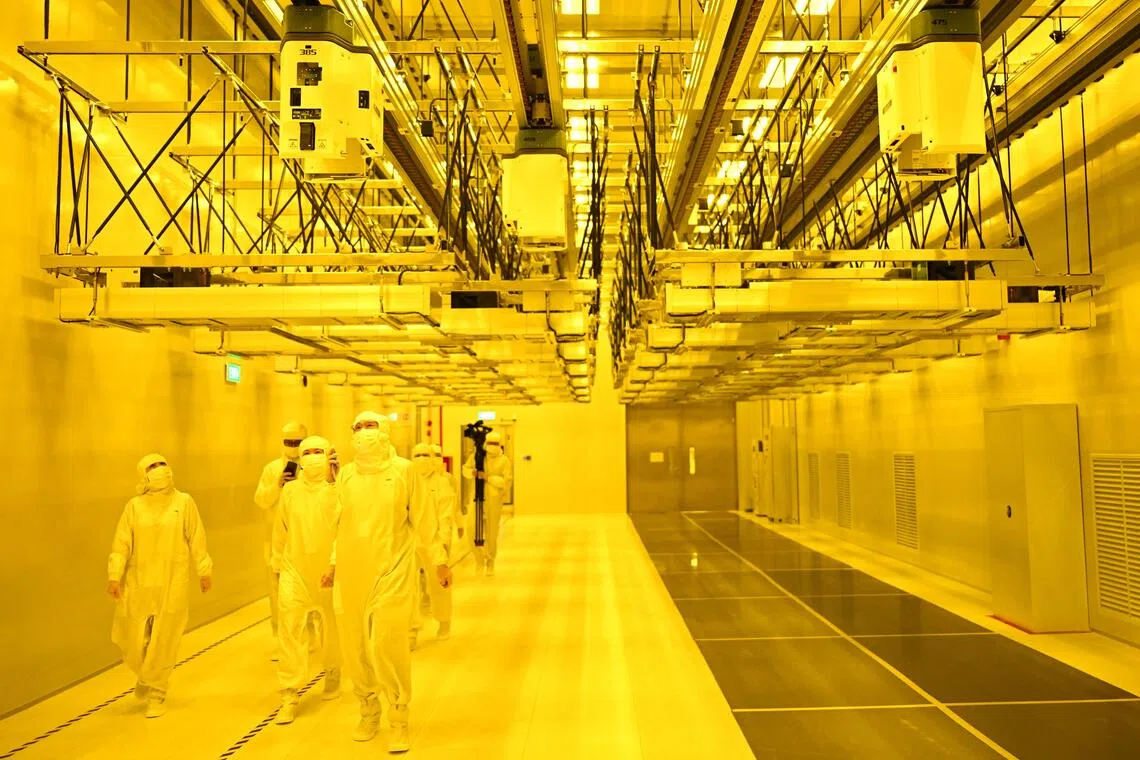
Silicon Box runs a panel-level packaging plant in the Wafer Fab Park there, built for around US$2 billion. A few minutes away, VisionPower Semiconductor Manufacturing Company (VSMC), a joint venture between Taiwan’s Vanguard and Dutch chipmaker NXP, is putting up Singapore’s first 12-inch wafer fab.
In June, Applied Materials opened a S$600 million campus in the same district that more than doubled its cleanroom space here.
None of the three is listed on the Singapore Exchange (SGX). That contrast sits at the heart of the standard complaint about Singapore’s chip sector: the state has spent four decades building a physical ecosystem with foreign direct investment, while local equity markets wait patiently for the listed proxies to catch up.
But look at the board, and the gap between Tampines cleanrooms and Shenton Way ticker tape is narrowing quickly.
AEM , for example, reported first-half net profit of S$31 million, up 904 per cent from a year earlier, on revenue of S$247.2 million. It also lifted full-year revenue guidance to between S$630 million and S$680 million.
The test solutions provider’s share price started 2026 at around S$1.70, and was trading nearly five times that by early August.
UMS Integration posted second-quarter revenue of S$87.1 million and net profit of S$19.4 million, up 29 per cent and 89 per cent, respectively, with its share price more than doubling this year.
These are not chip designers competing with Nvidia, nor foundries trying to outgun Taiwan Semiconductor Manufacturing Company.
SEE ALSO
Singapore’s listed cluster can be sorted into five distinct layers:
- Test and validation, where AEM sits alongside Sunright and Avi-Tech ;
- Equipment and precision parts, covering UMS, Frencken Group and Manufacturing Integration Technology ;
- Consumables and materials, including Micro-Mechanics , Nanofilm and Ellipsiz ;
- Industrial automation, where CSE Global and ISDN operate; and
- Hardware manufacturing, the domain of Venture Corporation , PC Partner , Valuetronics , Aztech and InnoTek .
Institutional capital is tracking that division closely. SGX data shows year-to-date net institutional inflows into the technology sector were strongest in the production layer, led by AEM and followed by Frencken and PC Partner.
Even Venture, the laggard of the group, worked through three years of falling revenue before returning to growth in the first quarter on an 11 per cent rise in artificial intelligence infrastructure products.
The technical reasoning for this cash flow is straightforward. Shrinking transistors is getting harder and more expensive, so more of the performance gain now comes from how logic, high-bandwidth memory, chiplets and photonics are put together.
That pushes value downstream towards advanced packaging, testing, interconnect and thermal management.
Structurally favourable shift
Merrill Tan, executive director for equity research at AR Capital, called the shift “structurally favourable for Singapore”, since those are the exact areas the country already works in.
The way he sees it, AI systems depend entirely on how well components run together at high power densities.
He said: “System performance therefore depends not only on the capabilities of individual components, but also on how effectively they are packaged, interconnected, cooled and tested, making areas such as advanced packaging, testing and thermal management much more critical to overall system performance and reliability.”
As those systems get more valuable, the price of getting them wrong climbs with them.
“As system complexity and value increase, so does the cost of yield losses or reliability failures,” he noted.
A ruined package is a much bigger problem when it is worth tens of thousands of dollars and sits in a data centre nobody can easily reach. That is where the supplier’s leverage lies.
“Suppliers that can materially improve yield, reliability, throughput, power efficiency or performance will therefore potentially achieve stronger and more defensible economics, particularly once they are qualified into a critical customer platform or production process,” Tan said.
Getting designed into a critical process takes years and is disruptive to undo.
Singapore’s physical moat underpins this listed strength. Its early commitment to semiconductor manufacturing brought in Micron and Applied Materials, and established manufacturers such as GlobalFoundries have continued to expand here since.
“Singapore’s most defensible advantage is the depth of its semiconductor ecosystem, built over several decades,” said Tan.
Those investments, he added, have created “a mutually reinforcing cluster of specialised suppliers, infrastructure, engineering talent and R&D capabilities that are difficult to replicate quickly”.
The country secured S$30 billion of semiconductor investment between 2022 and 2025, pushing semiconductors to roughly 7 per cent of gross domestic product.
Tan expects that advantage to hold as the industry matures, because complexity and supply-chain resilience push companies towards places with reliable execution, skilled talent and established suppliers.
Singapore’s advantage, he noted, “rests on the strength of the ecosystem as a whole, rather than simply cheaper land or larger subsidies”.
Policy and private capital have followed. Budget 2026 committed S$800 million to a flagship programme in semiconductors, aimed at advanced packaging and photonics.
Meanwhile, Micron broke ground in January on an advanced wafer fab worth about US$24 billion over a decade, and United Microelectronics Corporation’s US$5 billion Fab12i P3 facility begins phase-one production this year.
Moving up the chain
For the companies already here, Tan’s read is that the opening is to climb.
The opportunity, he said, is “to move into more technically demanding and critical parts of the production process”, where becoming embedded in a customer’s development and production work is what earns the better economics.
The listed universe has changed more quickly this year than in the decade before it to reflect this.
Ambiq Micro took a secondary listing on the SGX mainboard in July. The Texas company designs ultra-low-power chips for edge AI and is the first sizeable global fabless chip designer on the board.
PC Partner went the other way, delisting from Hong Kong in January to trade only here.
Frencken raised about S$100 million in late August via a placement. Its buyers included four managers appointed under the Monetary Authority of Singapore’s S$6.5 billion Equity Market Development Programme, a clear sign of strong interest from domestic money to fund this end of the market.
Private companies are also looking this way. Mi Material, the semiconductor materials arm of Malaysia’s Mi Technovation, received conditional eligibility to list here on Aug 25.
The company is a leading provider of solder spheres globally, enabling performance-critical interconnect solutions in advanced semiconductor packaging.
It focuses on precision miniaturisation – with fine and ultra-fine pitch solder sphere capabilities – which support higher-density memory packaging.
Simultaneously, its advanced materials science capabilities, with proprietary alloy formulations, enable demanding packaging applications.
“We would like to see SGX increasingly reflect the technology ecosystem that Singapore has already built in the real economy.”
Merrill Tan, executive director for equity research at AR Capital
Elsewhere in the advanced manufacturing value chain, Emage Group started in 2011 building custom optical systems for eye-care manufacturers, solving the awkward problem of inspecting a curved, transparent contact lens.
Its founder Wong Soon Wei makes the same point Tan does about qualification, from the other side: prove a system in a tightly regulated industry, and it rolls out across the customer’s sites without being re-evaluated each time.
Emage has stayed profitable since its first year. It focuses now on physical AI by producing AI-driven industrial robots for factory automation.
Its chairman Charles Cher – a former chief executive of AEM – has stated publicly that Emage may consider an initial public offering on SGX when it needs capital to scale globally.
Benjamin Lim, a senior analyst at pvtIQ, Smartkarma’s private markets research arm, observed that Emage “remains relatively small in absolute scale, but could become a listing candidate if it scales materially or demonstrates a clear path to doing so”.
He applies the same test to the larger names. Silicon Box has had a busier 2026 with further financing, a production ramp and expansion, but the analyst noted that “disclosure on financial performance and operating metrics remains limited, so we await greater visibility before assessing its IPO readiness”.
VSMC is, again, a different case. As a strategic joint venture, Lim said, any listing “would likely depend more on the shareholders’ capital and strategic requirements”, including whether there is any reason to bring in outside investors.
What gives him confidence is precedent. Singapore has a long history of advanced-manufacturing and precision-engineering companies that have listed successfully, which he reads as a template for the current crop.
Closing the gap
Lim also reframed the usual question. “We see it as less of a choice between listing on Nasdaq or remaining private, and more of a choice between going public or staying private,” he said.
Staying private buys time to scale, build a financial track record and prepare for public investors, and private capital has become considerably easier to access over the past two decades.
When a company does go public, he noted, the key consideration is “access to the right investor base rather than simply the exchange itself”.
In his view, the local technology investor base, proximity to the broader Asian semiconductor ecosystem and a track record with listed technology and precision engineering companies are all real advantages.
The variable is the company, and whether it has the scale, liquidity and growth story to use them.
There is a subtler obstacle too, which is that investors have to understand what they are buying. Lim considers the sector as under-covered rather than ignored.
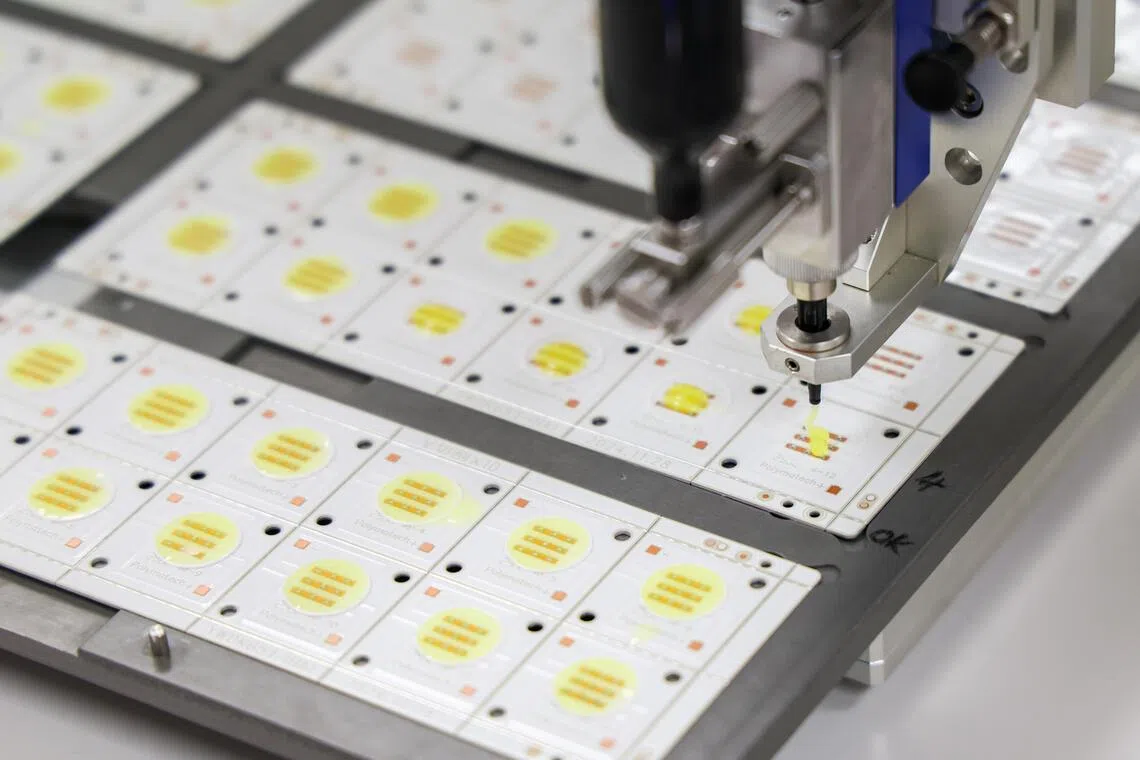
“Some of these businesses and business models are not necessarily straightforward to understand and can require specialist knowledge of areas such as semiconductors, advanced manufacturing or the broader technology supply chain,” he said.
That makes investor education and access particularly important, and he expects better disclosure, research coverage and engagement to close the gap as more of these companies become visible.
On whether the AI cycle has changed how global institutions view Singapore, he remains careful. It has brought more attention, though “this has been more of a selective rerating than a wholesale change”.
The opportunity, he said, is to “translate that strategic importance into more investable companies”.
Both Lim and AR Capital’s Tan land in a similar place from different directions.
“We would like to see SGX increasingly reflect the technology ecosystem that Singapore has already built in the real economy,” Tan said, referring to the listing of companies already embedded in the value chain operating here.
The point, he added, is not simply a bigger count of technology listings, but also “companies with a clear and differentiated value proposition” in areas with genuine structural growth.
After that, the requirements are the familiar ones. Institutional investors, Tan noted, look for “sufficient scale and liquidity, strong governance and disclosure, disciplined capital allocation and a demonstrated ability to deliver sustainable earnings and cash flow growth”.
Which brings it back to Tampines. The gap between what Singapore builds and what Singapore lists is real – but it is narrower this year than last.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.